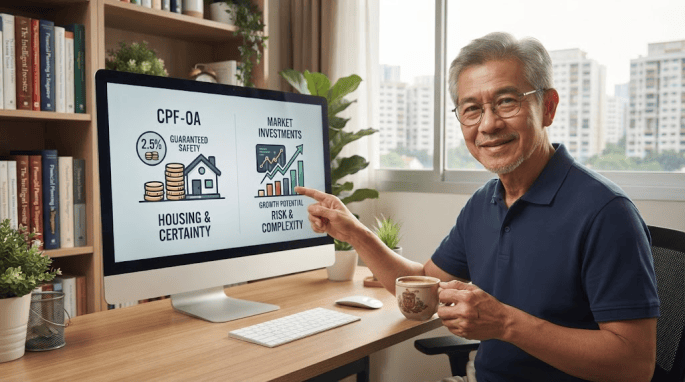
When it comes to personal finance in Singapore, conventional wisdom often pushes investors to maximize returns by deploying every available dollar. For the Ordinary Account (OA) under the Central Provident Fund (CPF), which earns a baseline 2.5% per annum, many assume that leaving funds untouched is an unnecessary opportunity cost compared to what a diversified … Continue reading Why This Investor Does Not Invest His CPF-OA (And When It Might Make Sense for You)
Legal Disclosure: I’m not a financial advisor. The information contained in this blog is for sharing purposes only. Before investing, please consult a licensed professional. Any stock purchases I show on my blog should not be considered “investment recommendations”. I shall not be held liable for any losses you may incur for investing and trading in the stock market in an attempt to mirror what I do. Unless investments are FDIC insured, they may decline in value and/or disappear entirely. Please be careful!